Boring is not enough. I built a formula for separating ordinary businesses from genuinely attractive opportunities.
For a long time, I thought “boring” was a useful filter for finding businesses worth building. I still think it is, but I no longer think it is enough. There are plenty of boring businesses that I would never want to own.
A business can be unglamorous and still have terrible margins. It can solve a real problem and still be difficult to scale. It can generate revenue and still require the owner to be involved in every quote, every job and every customer complaint. It can have recurring demand while being so geographically dispersed that half the working day disappears into traffic.
A terrible business can be boring too.
What I have become increasingly interested in is not whether a business is exciting or boring, but whether it has good underlying economics. That is a very different question, and the more service businesses I build, study and operate, the more convinced I become that opportunity quality can be evaluated far more systematically than most entrepreneurs realise.
Not perfectly. There will always be judgement involved. But certainly better than simply saying, “This seems like a good business.”
So I built a scorecard. It asks ten questions before I put serious time, capital or attention behind a service-business opportunity. Interestingly, the business that led me down this path, gutter cleaning, scores about 82 out of 100.
That is not because gutter cleaning is the greatest business in the world. It’s because its weaknesses are manageable and its strengths reinforce one another. That distinction matters.
The mistake is evaluating the service instead of the business
Entrepreneurs naturally look at what a company sells: window cleaning, pool maintenance, painting, pest control, landscaping, gutter cleaning, plumbing or roof repairs. But the service itself tells you surprisingly little about whether the underlying business is attractive.
Two businesses performing almost identical work can have completely different economics. One operator might drive 15 kilometres between every customer while another services eight properties inside the same neighbourhood. One might depend on once-off emergency jobs while another has customers automatically scheduled every month. One might require the founder to diagnose every problem while another can train a technician using a documented process. One might own R2 million worth of machinery before earning the first rand, while another might start with equipment that fits inside a small vehicle.
So when I evaluate an opportunity now, I try to separate the service from the business model surrounding the service.
The question is not simply, “Is pool cleaning a good business?” The better question is, “Under what conditions does pool cleaning become a good business?”
That immediately forces a better conversation.
The ten variables
My current model evaluates an opportunity across ten variables. Each variable is scored from 1 to 10, but they are not weighted equally because some factors matter more to me than others.
| Variable | Weight | What I am really asking |
|---|---|---|
| Demand | 15% | Do enough people genuinely need this? |
| Margin | 15% | Is there enough economic room between price and delivery cost? |
| Service Frequency | 10% | How often does the problem return? |
| Labour Complexity | 10% | How difficult is execution to teach, supervise and standardise? |
| Capital Intensity | 8% | How much money must be committed before revenue can be produced? |
| Regulation | 5% | How much licensing, compliance or specialist certification sits between us and execution? |
| Route Density | 10% | Can customers be served efficiently inside concentrated territories? |
| Upsell Potential | 7% | Does solving one problem naturally expose other valuable problems? |
| Recurring Revenue | 10% | Can revenue become predictable rather than repeatedly reacquired? |
| Owner Independence | 10% | Can the business eventually function without the founder? |
The total gives me what I call the Boring Business Opportunity Score.
It is not a scientific law. It is a decision-making instrument. The purpose is not to make judgement disappear, but to stop emotion from hiding the trade-offs.
Demand comes first
A great business model attached to weak demand is still a weak opportunity, so demand comes first. I want problems that already exist, which is one of the reasons I remain attracted to boring businesses in the first place.
You do not have to convince somebody that roofs get dirty, grass grows, pools need maintaining, gutters collect debris, windows become dirty or plumbing eventually fails. The underlying problem exists independently of the entrepreneur.
That matters enormously because there is a difference between capturing demand and creating demand. Both can build enormous companies, but creating demand normally requires more education, more marketing, more time and more capital. For the kinds of businesses I am interested in, I would rather begin with something people already understand and then compete on execution.
Demand, however, cannot simply mean that somebody somewhere needs the service. I want to know how many customers exist, how urgently they experience the problem, whether they are willing to outsource it and whether there is enough purchasing power in the target geography.
A massive theoretical market with weak willingness to pay can be worse than a smaller market with a painful problem and strong purchasing intent.
Margin creates room for mistakes
The second variable is margin. This sounds obvious, but revenue has a strange psychological effect on entrepreneurs. A business doing R1 million per month can sound more impressive than one doing R400,000 until you discover that the first business keeps R50,000 and the second keeps R120,000.
Revenue is useful, but economic surplus is what gives the business room to breathe. A healthy margin creates capacity for marketing, management, technology, vehicles, insurance, quality control, rework and eventually profit.
Thin margins force perfection, and small service businesses are rarely perfect. People arrive late. Vehicles break. Weather changes. Customers reschedule. Jobs take longer than expected. Materials cost more than expected. Somebody has to return to a property.
The margin must absorb reality.
This is one reason I have become increasingly cautious about opportunities where the pricing ceiling is low but labour intensity is high. The business may technically work, but there is very little room between a good day and an unprofitable one.
Frequency changes everything
Then comes frequency. How quickly does the problem regenerate after you solve it?
Consider the difference between cleaning a swimming pool and replacing a roof. A roof replacement might produce a large invoice, but the customer may not need another roof from you for decades. Pool maintenance can potentially occur every week.
That creates completely different economics. The customer acquisition cost can be spread over dozens of future visits, scheduling becomes predictable, technician utilisation becomes easier to forecast and revenue starts every month with something already on the books.
Gutter cleaning is weaker on this variable. In many properties, the need may only arise once or twice a year, with more frequent cleaning where trees, debris or local conditions make it necessary.
That is not fatal. It simply means the rest of the model has to compensate.
There is no single magic variable. Opportunity quality is a portfolio of trade-offs.
Labour complexity is one of the most underestimated variables
This one has become increasingly important to me through HomeCare. There are services that look fantastic on paper until you try to execute them consistently through other people.
The problem is not necessarily that the physical work is difficult. The problem is often variance.
How many different judgement calls can occur during the job? How long does competency take to develop? How much supervision is required? How expensive is a mistake? How easy is it for two technicians to arrive at completely different conclusions?
I have seen this even within the gutter category.
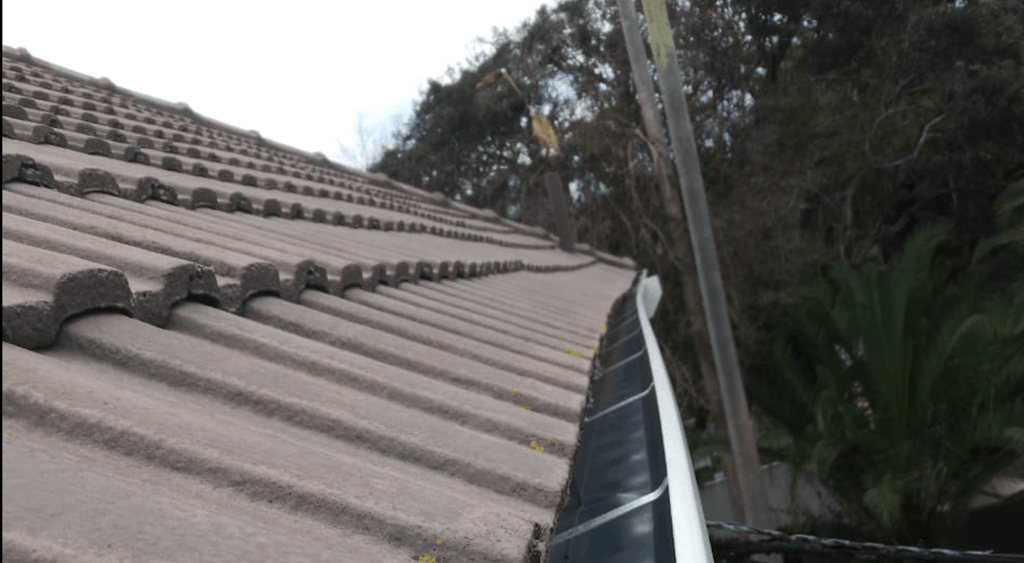
Cleaning is relatively bounded. There is a gutter system. It contains debris. The job is to remove the debris, ensure the system is flowing correctly, inspect what is visible, document the work and leave the property clean.
Minor repairs appear closely related, but commercially they are a different animal. Suddenly you have diagnosis, material matching, old systems, unusual fittings, access complications, unknown historical workmanship, scope uncertainty and much greater potential for a technician to make a judgement call that creates downstream consequences.
The invoice may be higher, but the operational entropy is also higher.
That is why I increasingly distinguish between businesses that merely produce good gross margins and businesses that can produce good gross margins repeatably through ordinary trained people. Those are not the same thing.
Capital intensity determines how expensive learning becomes
Every new business contains uncertainty. The more capital required before you can test your assumptions, the more expensive your mistakes become.
This is why I like opportunities where the first version can be launched lean. If one business requires a vehicle, basic equipment, insurance and a small team, while another requires a facility, specialised machinery, expensive inventory, permits and several full-time employees before the first customer arrives, the second business may still ultimately become larger. But the first allows you to purchase information more cheaply.
You can test pricing. You can test demand. You can test advertisements, technicians, neighbourhoods and the service process itself. You can learn what customers actually value before committing heavily to infrastructure.
Then, once reality has replaced assumption, you can invest more capital with greater confidence.
That option has enormous value.
Regulation is neither automatically good nor bad
Regulation can create barriers to entry, but it can also create bureaucracy, liability and dependencies that slow expansion. The important thing is to know what you are buying into.
Consider pest control. It looks like a classic boring business: real demand, repeat customers, route density and clear household pain. But it also sits inside a more formal regulatory structure than something like basic exterior cleaning.
That does not make pest control unattractive. It simply changes the score.
Depending on your strategy, a regulatory barrier may even become an advantage because competitors cannot enter as casually. The important question is not, “Is regulation bad?” It is, “How much complexity does regulation introduce into this particular operating model?”
That is the kind of distinction the scorecard is designed to force.
Route density is invisible until it destroys your margin
I think this is one of the least appreciated variables in local service businesses. You can have customers, good pricing and even good gross margins at job level and still build a terrible business because your technicians spend half their working lives driving.
The map matters.
Suppose a technician completes four R1,000 jobs in a day. That is R4,000 in revenue. Now suppose the same technician can complete six because the customers live within a tightly concentrated service area. That becomes R6,000 of revenue from effectively the same working day, vehicle and employee.
Nothing changed about the service. The geography changed.
This is why I think service companies eventually need to stop viewing growth purely as “more customers”. A customer that strengthens an existing route can be economically more valuable than an identical customer 40 kilometres away.
This has influenced how I think about HomeCare enormously. The long-term goal is not simply to accumulate jobs across a city. It is to increase property density.
The more homes we serve inside the same suburbs, estates and neighbourhoods, the more efficient every subsequent service becomes. At sufficient density, geography itself becomes part of the moat.
I want businesses where one problem reveals the next problem
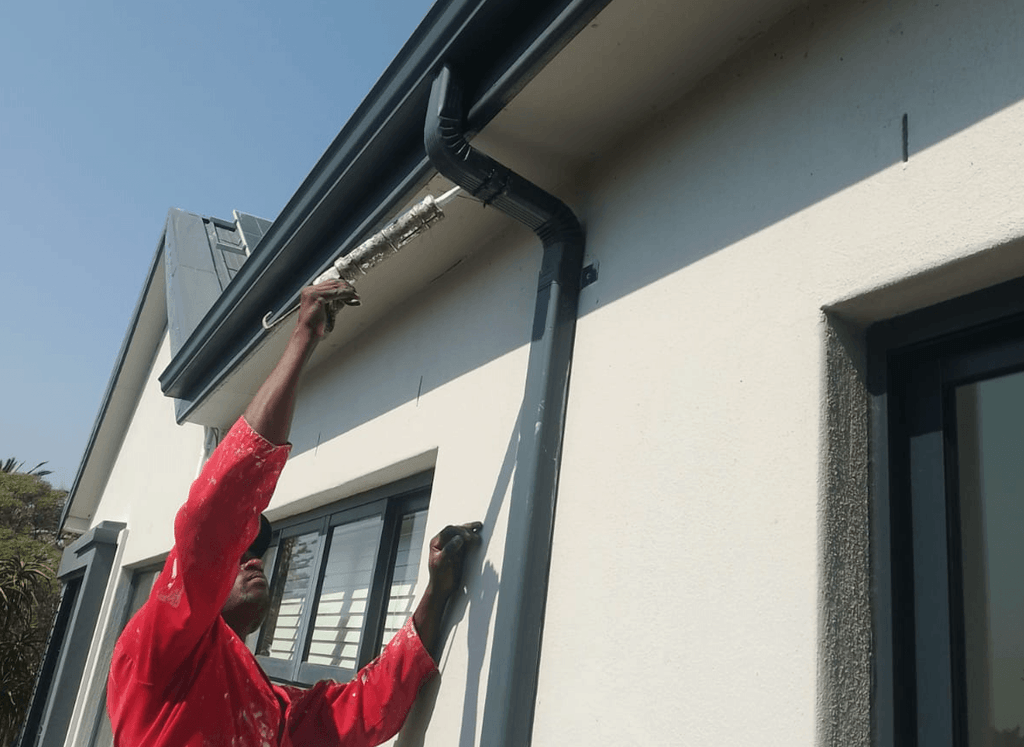
This is where gutter cleaning becomes much more interesting than it initially appears.
The customer thinks they are buying gutter cleaning. Operationally, we are gaining permission to inspect a system attached to one of the customer’s most valuable assets: their home.
While doing the work, we might observe gutter damage, drainage problems, roof debris, deteriorated components or other maintenance issues. That does not mean we should immediately sell every service we discover. In fact, I think that is exactly how companies lose strategic discipline.
But a strong entry service should create an information advantage.
It allows you to understand the property better. That creates legitimate opportunities for future maintenance, upgrades, recurring services or specialist referrals.
So I score opportunities higher when the initial service naturally creates the right to have another useful conversation. I think of this as commercial adjacency.
The strongest boring businesses often sit inside ecosystems of problems rather than isolated transactions.
Recurring revenue is different from repeat revenue
This distinction matters.
A customer who might call you again is not recurring revenue. A customer who gets their gutters cleaned every year is repeat revenue. A customer enrolled into a scheduled maintenance programme is much closer to recurring revenue.
Each step reduces uncertainty, and that matters operationally because predictable revenue changes what the company can confidently commit to.
Employees. Vehicles. Software. Management. Marketing. Infrastructure.
It also matters to the eventual transferability of the company because predictable revenue makes the future of the business less dependent on continuously reacquiring customers from scratch.
That leads directly into the final variable.
The business eventually needs to stop needing you
This may be the most important variable in the entire framework.
Does the opportunity lend itself to becoming a company, or does it naturally become self-employment with staff?
There is nothing wrong with self-employment, but it is a different asset.
If customers only trust the founder, the founder must sell. If the founder must inspect every job, the founder must inspect. If pricing lives inside the founder’s head, the founder must quote. If only the founder knows which technician can handle which job, the founder must dispatch. If problems always escalate to the founder, the founder remains the operating system.
Eventually the company reaches a ceiling determined by one person’s attention.
That is why I score opportunities partly on their potential for owner independence before I even start them.
Can the work be documented? Can quality be measured? Can people be trained? Can decisions be converted into rules? Can customer trust move from the individual to the institution? Can the operating knowledge become software, process and documentation?
If the answer is yes, you are potentially building an asset.
If the answer remains no, you may simply be building yourself a more complicated job.
So why does gutter cleaning score 82/100?
Using the current version of my model, this is roughly how I score the business:
| Variable | Weight | Score | Weighted Result |
|---|---|---|---|
| Demand | 15% | 9/10 | 13.5 |
| Margin | 15% | 9/10 | 13.5 |
| Service Frequency | 10% | 5/10 | 5.0 |
| Labour Simplicity | 10% | 8/10 | 8.0 |
| Low Capital Intensity | 8% | 9/10 | 7.2 |
| Low Regulatory Burden | 5% | 9/10 | 4.5 |
| Route Density Potential | 10% | 8/10 | 8.0 |
| Upsell Potential | 7% | 10/10 | 7.0 |
| Recurring Revenue Potential | 10% | 6/10 | 6.0 |
| Owner Independence Potential | 10% | 9/10 | 9.0 |
| Total | 100% | 81.7 / 100 |
Call it 82.
The number itself is less important than what produces it.
Gutter cleaning does not score particularly well on frequency, and that matters. A pool business, for example, potentially has dramatically better service frequency. But gutter cleaning compensates through relatively low startup capital, straightforward demand, good margins, bounded execution, low regulatory complexity and unusually strong commercial adjacency.
Most importantly, I can see a path from the founder performing the job, to a technician performing it, to a team following a documented system, to technology coordinating that system, to the customer relationship belonging to the company, and eventually to the business functioning independently of the founder.
That is what I am ultimately looking for.
A score is not a verdict
I want to be careful here because I do not believe entrepreneurs should simply plug ten numbers into a spreadsheet and start whichever business scores highest.
That would simply replace emotional decision-making with false precision.
A 78-point opportunity you understand deeply may be better for you than an 88-point opportunity where you have no knowledge, network or competitive advantage. Likewise, one exceptional characteristic can sometimes justify several weaknesses.
A heavily regulated industry may become attractive precisely because regulation reduces competition. A capital-intensive business may become extraordinary if those assets create a durable moat. A low-frequency service may still be excellent if the average transaction is extremely valuable.
The purpose of the formula is not to answer the question for you. It is to force you to ask better questions.
The real objective is not finding a business. It is building an asset.
I think this is where my own thinking has changed most.
The beginner asks, “What business should I start?”
The operator eventually asks, “How do I make this business profitable?”
But there is another question beyond both: “What would have to be true for this business to become a systemised, transferable asset?”
Those are three completely different stages.
An idea is not a business. A business is not necessarily an asset. And an asset is not necessarily transferable.
The journey I am interested in looks something like this: Opportunity → Validation → Profitable Operation → Systemisation → Owner Independence → Transferable Asset
That is increasingly how I think about The Boring Business Academy as well.
The goal cannot simply be teaching someone to start a lawn business, cleaning company, gutter company or pool business. That only gets them onto the field.
The deeper transformation is learning how to take an ordinary service and progressively turn it into something that produces predictable economic value without depending entirely on the founder.
That is a much more interesting game.
Score one before you start one
I have turned the framework from this article into the first version of the Boring Business Opportunity Scorecard.
It walks through all ten variables, applies the weighting and forces you to write down the evidence behind each score. Not what you hope is true, but what you can actually demonstrate.
Because the biggest danger when evaluating a new business is not ignorance. It is enthusiasm.
Once we fall in love with an idea, we become remarkably good at producing evidence for why it should work. A framework gives us something to argue against.
So before you buy equipment, design the logo, register the domain or start running ads, score the opportunity.
You may discover that the boring little business you nearly ignored is much better than it looks. You may also discover that the exciting opportunity you have been obsessing over is simply a difficult job wearing a company logo.
Boring is not enough. The business still has to be good.
[Download the Boring Business Opportunity Scorecard V1 →]
Score one opportunity you are considering, then look at the weakest three variables. That is probably where the real business problem begins.